
Pillar 01 · Liquidity, matching & execution
Where corridor liquidity finds its price
Bank and non-bank liquidity aggregated into one book. Firm resting orders, strict price and time priority, and best-price selection across FX, precious metals, non-deliverable forwards and outright forwards.
MEX ECN · Aggregated bookLive Pricing
| Symbol | Bid | Bid Size | Ask | Ask Size | Spread |
|---|---|---|---|---|---|
| EUR/USD | 1.08420 | 25.0 | 1.08430 | 18.5 | 0.1 |
| USD/CHF | 0.79926 | 0.6 | 0.79930 | 1.4 | 0.4 |
| GBP/USD | 1.27100 | 15.0 | 1.27120 | 10.5 | 0.2 |
| USD/JPY | 149.820 | 500.0 | 149.850 | 410.0 | 2.0 |
| XAU/USD | 2 391.400 | 5.5 | 2 391.700 | 3.8 | 0.3 |
Firm resting orders · price and time priorityNo last look on resting orders
Sub-400nsMatching latency
$20B+Cleared daily
250+FX pairs
One book. Firm prices. Best price first.
Every order enters one central book. The engine evaluates price first, then time of arrival. The best-priced order executes first; among orders at the same price, the earliest executes first.
Priority is earned through price and time, not relationships. Resting central-order-book orders are firm, with no last look. Members stream, take or rest their own orders alongside providers, and the tightest quote surfaces automatically.
- Central order book with strict price and time priority
- No last look on resting central-order-book orders
- Aggregated bank and non-bank liquidity in one book25+ liquidity providers aggregated into one book
- Best-price selection on defined parameters
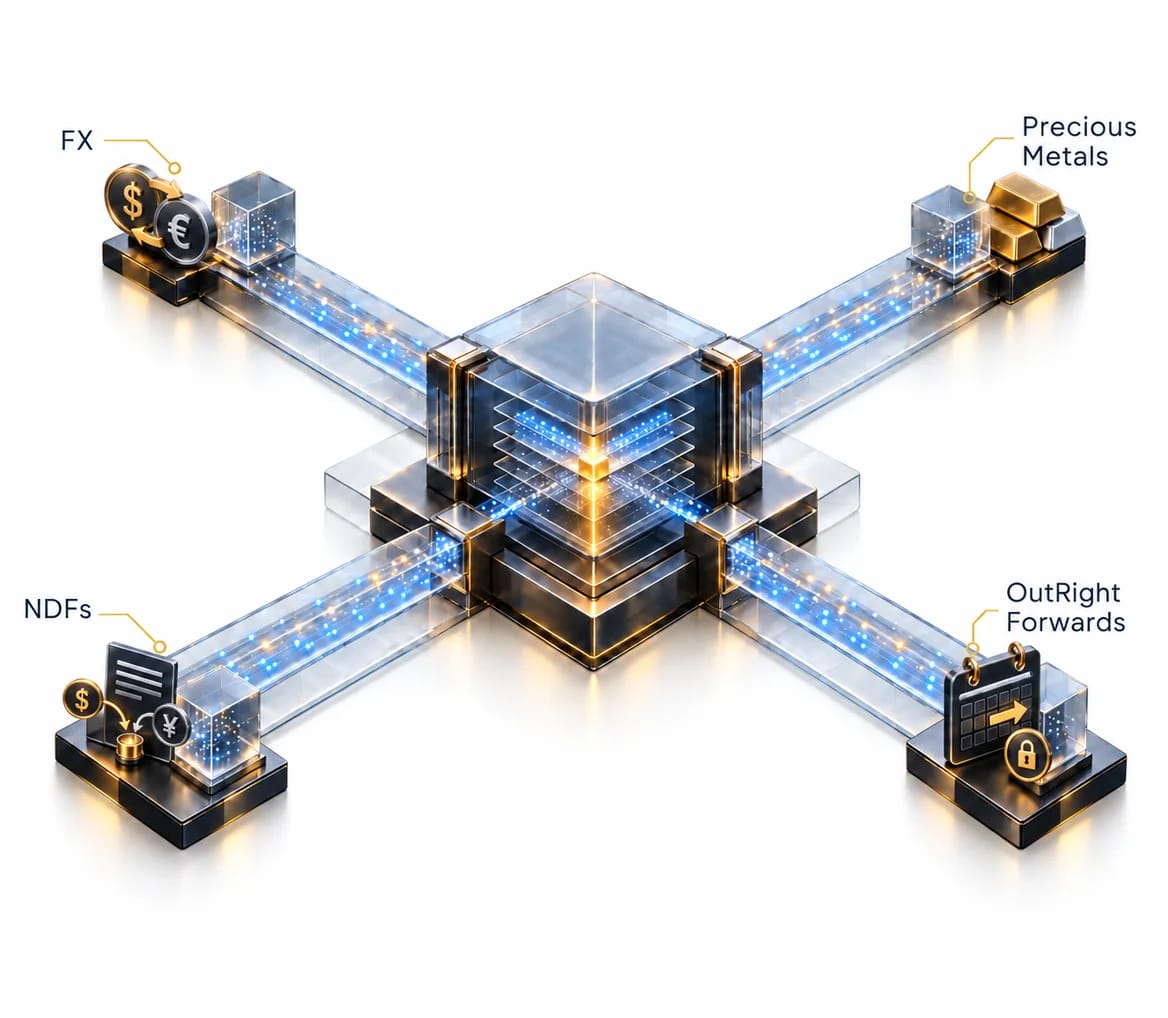
What membership includes
Four capabilities, one relationship
Price against the aggregated book
Request institutional access, or explore how credit and settlement complete the picture.